
Winery Insurance: The Questions Producers Should Ask and Coverages Buyers Should Know
A field guide for insurance producers, account managers, and winery owners.
A winery is four businesses standing on one piece of dirt: a farm, a manufacturer, a warehouse holding irreplaceable aging product, and a hospitality venue serving alcohol to the public. Most commercial policies are built for one of those. Writing winery insurance that answers only one of them is how coverage gaps get created.
If you are a producer or account manager looking at your first grape account, or an owner trying to understand what you are actually buying, this is the map.
Why Winery Insurance Is Not a BOP With Grapes
Standard commercial forms assume a building, some contents, and a liability limit. A winery breaks that model in three places. The value is mobile and mutating. Juice becomes wine, gains value in barrel, and moves between tanks, storage, and tasting room. The equipment is often semi-custom and slow to replace. And the business invites the public onto an active production site and pours alcohol for them.
Ask the owner one framing question early: walk me from the vine; to the customer's glass and tell me every place the wine stops. Each stop is an exposure, and it surfaces things a standard application never asks.
Vineyard Insurance Versus Winery Insurance
This distinction trips up new producers, and it matters at the submission stage.
A vineyard is an agricultural operation. The exposures are growing exposures: vines, trellis, harvested fruit, ag equipment, chemical drift onto neighboring property, seasonal labor, and weather. It is usually the simpler half of the account.
A winery adds manufacturing, storage, retail, and hospitality on top: fermentation and temperature control, bottling lines, stored product (sometimes belonging to other people), a tasting bar, tours, and events. Underwriting complexity jumps considerably.
Most accounts are both, and that is where placement gets real. Split the account between an ag carrier and a commercial carrier and you create seam risk or the gap where a loss lands in neither policy. Berkley North Pacific writes wineries under a single policy rather than requiring separate vineyard and commercial policies, which removes that seam. Ask every market whether they can do the same, because a monoline patchwork is a claim waiting to be argued.
Property: Getting the Values Right on Specialty Equipment and Stock
Property is where under-insurance hides quietly until the day of the fire.
Buildings. Production facility, barrel room, crush pad, storage, tasting room, and often an estate dwelling.
Specialty equipment. Presses, destemmers, stainless tanks, chillers, bottling and labeling lines, forklifts. Much of this is built to spec or imported, and replacement cost is not what the owner paid five years ago. Long lead times mean a breakdown is also a business income event. Ask for a current equipment schedule with real replacement quotes, not depreciated book value.
Vines and trellis. These are property and they are frequently omitted. Trellis coverage is a standard winery insurance extension with sub limits and belongs on the schedule.
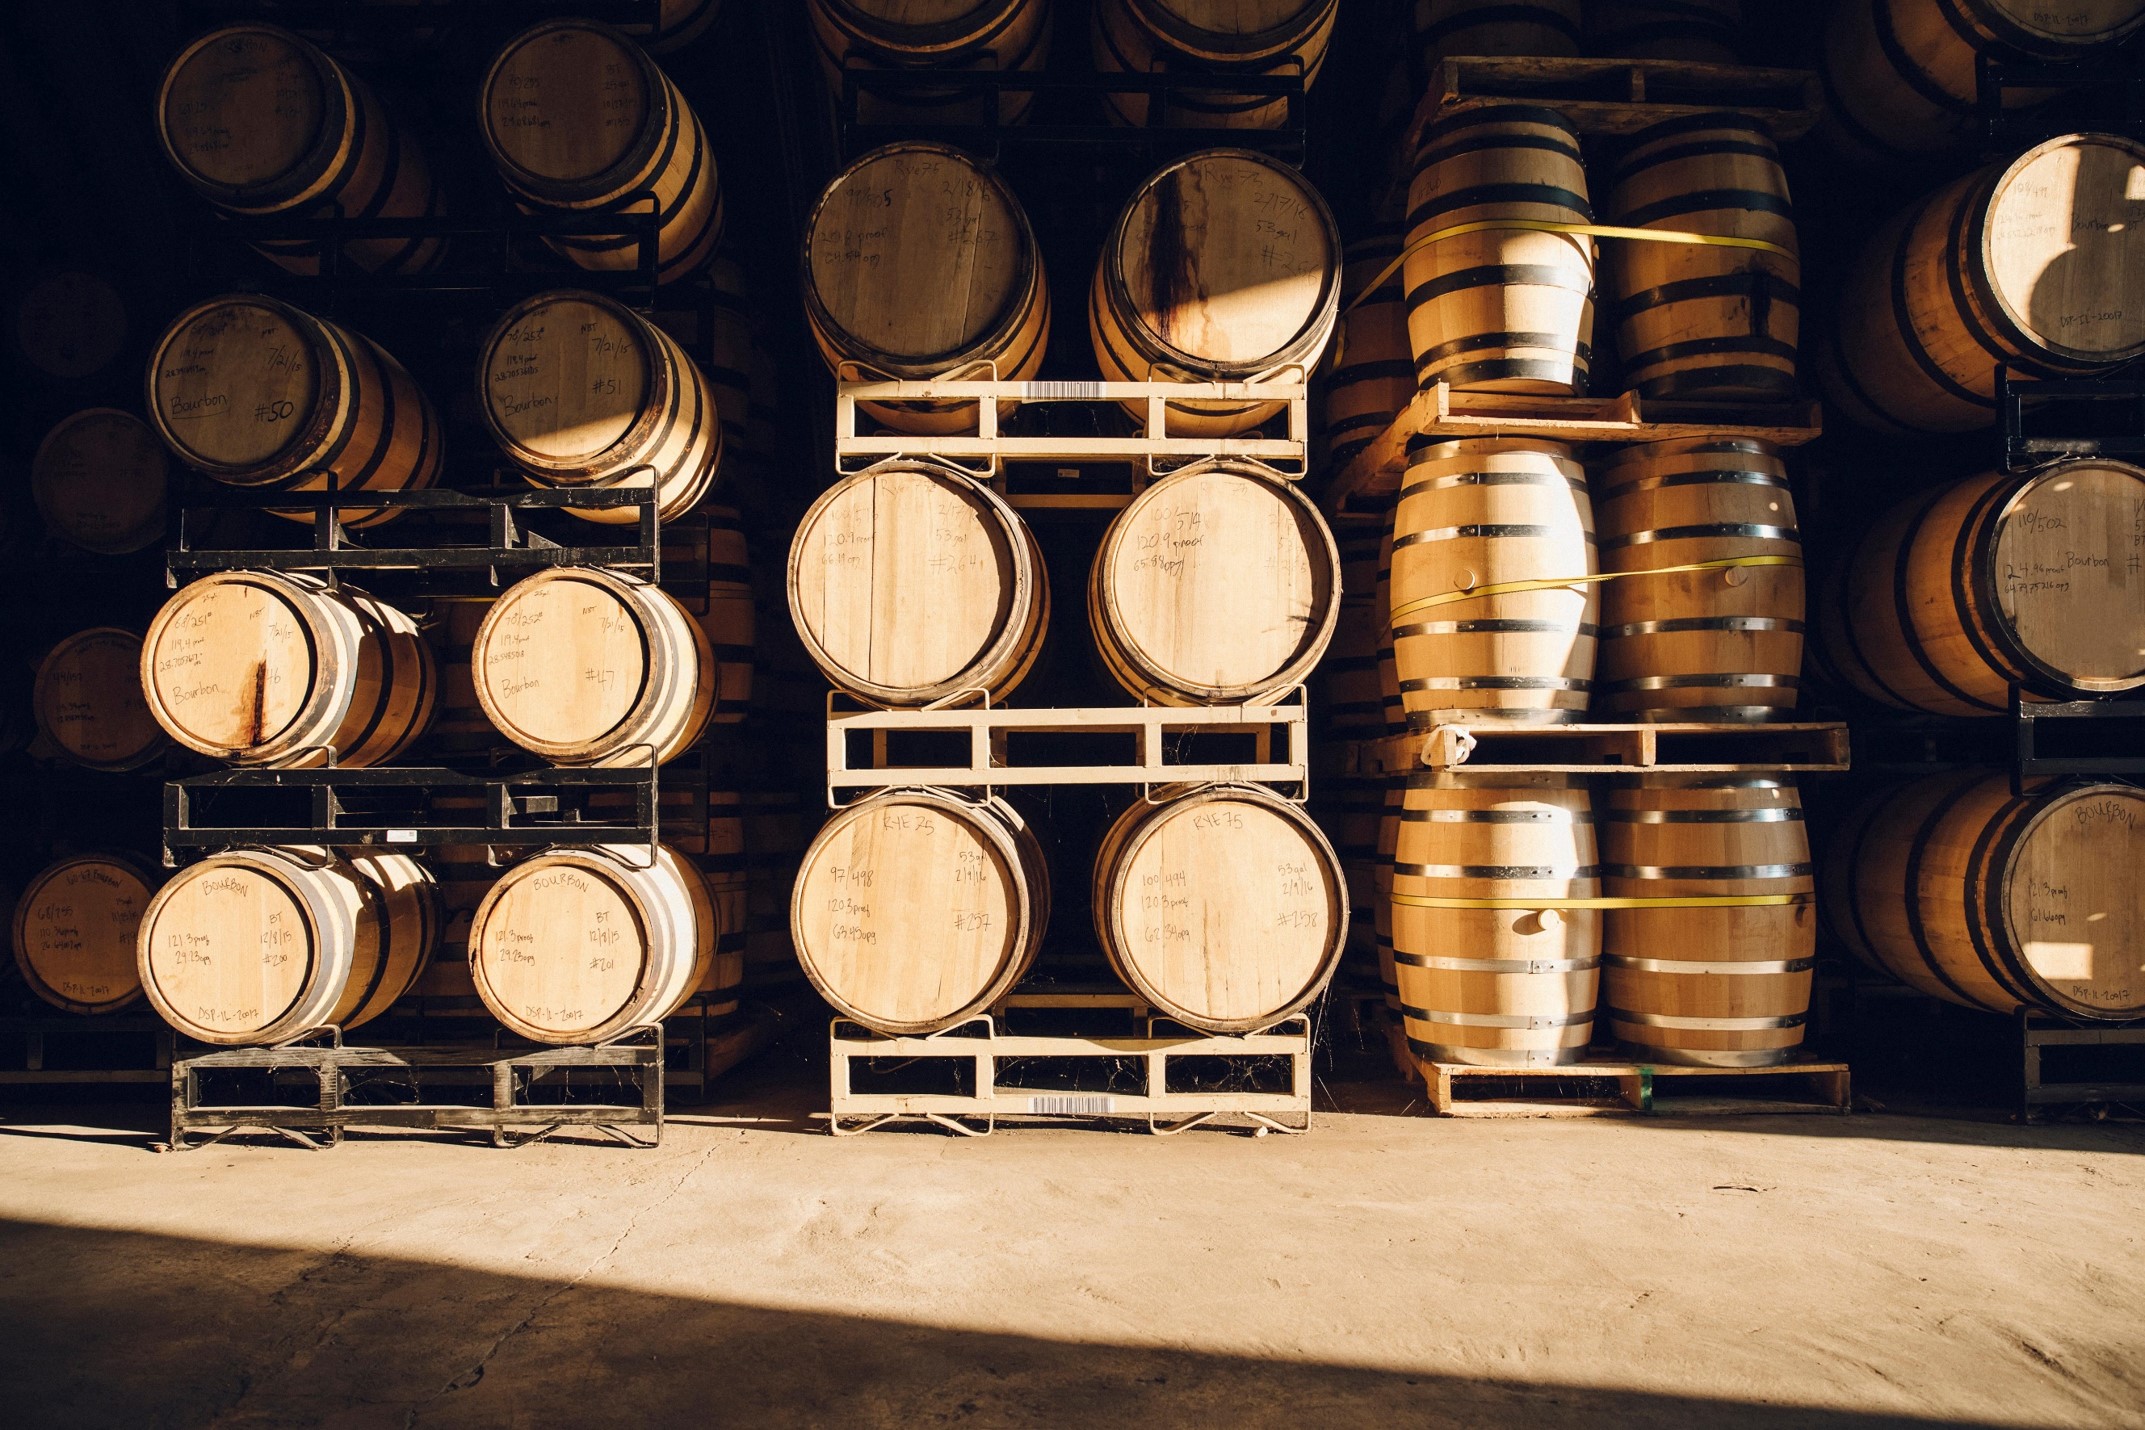
Stock, and where it lives. Wine in process, wine in barrel, and bottled inventory carry very different values. Bottled wine should be valued at market; the grape cost does not come close to the value of a finished case. Then ask the question producers forget: where else is wine stored? Off-site warehouses, custom crush facilities, wine held for other producers, wine in transit. These locations are often overlooked during the valuation process but can represent significant insured values that may require scheduled locations or consideration of Property at Other Locations limits.
Peak season. Inventory values swing dramatically between pre-harvest and post-bottling. A flat limit set in February will be badly wrong in October.
Contamination, Leakage, and Product Withdrawal
Contamination is the loss that surprises first-time buyers, because nothing looks broken. A cooling failure, cork taint, or a sanitation error can destroy a vintage that is physically still sitting in the tank.
Confirm these on the quote:
- Wine contamination — product rendered unmerchantable
- Wine leakage — tank, barrel, hose, and valve failures; more common than owners expect
- Product withdrawal or recall expense — the cost of pulling product off shelves
- Product liability — claims from the wine once it is out of your control
- Brands and labels expense — so salvaged product isn't resold under the winery's name
Ask specifically whether wine in process is covered, not just finished stock. Trigger language varies meaningfully between carriers, and in-process product is often where the largest concentrated value sits.
Equipment Breakdown Coverage
Equipment breakdown coverage responds to mechanical, electrical, and pressure failures that a standard property form likely excludes. At a winery, the loss almost never stops at the machine.
A glycol chiller fails during fermentation. The repair is a modest invoice. The tank of ruined wine behind it is the real loss, plus the income from a vintage that no longer exists. Confirm the form includes spoilage resulting from breakdown, and that business income sits behind it with a period of restoration that reflects real equipment lead times.
Ask: How old are the chillers and compressors? Is there a preventive maintenance program? Temperature alarms and backup power? Wineries with documented maintenance present better and often price better.
Liquor Liability and Entertaining on the Property
A tasting room is a bar. From a claims standpoint there is typically no distinction, and general liability generally excludes alcohol-related claims, so liquor liability needs its own limit. Host liquor language buried in a GL form likely does not cover a business whose model is selling and serving alcohol.
Match the limit to volume and hours. A winery pouring tastings until nine on summer Fridays is a very different risk than one open Saturday afternoons by appointment.
Then there is agritainment, the revenue driver almost every small winery has added. Weddings, live music, food trucks, farm dinners, and crush and release parties. Every one of those changes the risk profile.
Work through these with the owner:
- What events do you host, how often, and what is peak attendance?
- Who pours at a private event — your staff or a third-party caterer?
- Do you require certificates of insurance and additional insured status from vendors, caterers, and bands? Spoiler alert, you should.
- Is there a written contract with indemnification and hold-harmless language?
- Is parking on grass, at night? Lighting and marked walkways?
- Do guests walk through the active production area, near forklifts, tanks, and hoses?
-
Is server training documented, and is the liquor license in good standing? Coverage typically will not respond on a lapsed license.
BNP can accommodate many agritainment exposures like weddings, live music, crush and release events, but it’s best to disclose actual and intended events to make sure the right coverages are aligned to the policy.
Don't Forget the Fundamentals
Specialty coverages get the attention, but a winery insurance program still rests on the basics: general liability for visitors and tours, workers compensation for production, vineyard, and tasting room staff, commercial auto including hired and non-owned for self-delivery, inland marine for product in transit, cyber for the wine club and e-commerce platform, and umbrella limits sized against liquor and product severity rather than premises frequency.
People Also Ask
What does winery insurance typically cover?
Property on buildings, custom equipment, tanks, barrels, vines, and trellis; stock including wine in process and finished inventory; general liability; liquor liability; product liability and recall; contamination and leakage; equipment breakdown coverage; business income; commercial auto; and workers compensation. Winery insurance is a package built from these parts, not a single policy.
Do I need liquor liability if I only pour small tasting samples?
Yes. Serving any amount of alcohol to the public creates dram shop exposure, and general liability likely will not respond to it. Sample size is not the standard — over-service and the resulting injury is.
Is crop or vine damage covered under winery insurance?
Partly. Vines and trellis (with sub limits) can usually be scheduled as property against perils like fire and vandalism. Yield loss from frost, hail, drought, pests, or disease is generally handled separately through crop insurance or MPCI, so confirm what is and is not in the package.
Does my policy cover wine stored off-site or in transit?
Only if it is scheduled and subject to limits. Off-premises storage, custom crush locations, wine held for others, and transit all need to be disclosed and endorsed. Have a discussion with your underwriter if the underlying limits are not enough.
Ready for a Quote? Here Is What to Have Ready
The fastest way to find out whether your program has gaps is a full winery insurance review with an independent agent who knows grape accounts. Use our agent locator to find one near you, or ask your BNP business development manager or underwriter for an introduction.
Bring these to the conversation and you will get a faster, sharper quote:
- Annual sales and gallons produced — the two numbers that drive the winery supplemental application. We can even consider bottles or cases
- Revenue split — production, wholesale and distribution, tasting room, events, retail, food, lodging
- Property schedule — buildings, equipment with replacement values, vines and trellis, planted acreage
- Stock values — in-process, barrel, and bottled, with peak-season high and off-site or stored-for-others locations listed
- Event detail — types, frequency, attendance, who pours, vendor COI requirements
- Licensing and training — current liquor license and server training records
- Loss runs — five years, currently valued
- Risk controls — sprinklers, temperature alarms, backup power, preventive maintenance records, security
Underwriters price uncertainty. The surest way to a better quote is a complete picture that leaves nothing for them to guess at through your application submission.
What To Expect With Berkley North Pacific
Once you have gathered the correct information and completed an Acord Application, you will also want to fill out the winery supplemental which can be found in our agency portal. Be sure you are asking whether you want the policy rated on sales, gallons, or bottles produced.
It's now time to send the submission to your underwriter. If you have any specific outliers like types of entertainment, be sure to have a narrative ready so you can speed up the process. If you are looking to prospect wineries, be sure to contact your underwriter or business development manager for more details on our appetite.
Products and services of Berkley North Pacific described above are provided by one or more insurance company subsidiaries of W. R. Berkley Corporation. Not all products and services may be available in all jurisdictions, and the coverage provided by any insurer is subject to the actual terms and conditions of the policies issued. Information in this publication is subject to change at any time. This publication provides general information only, is not legal advice, and is not a statement of contract. While reasonable care has been utilized in compiling this information, no warranty or representation is made as to accuracy or completeness. Any statement regarding insurance coverage made herein is subject to all provisions and exclusions of the entire insurance policy. Claims scenarios are provided for example purposes only. The outcome of any claim is dependent on the specific facts and circumstances of the claim, as well as the policy provisions in effect at the time of the loss. Recipients of this material must utilize their own judgment in implementing sound risk management practices and procedures.
© 2026 Berkley North Pacific. All rights reserved.
Coverage Provided By: Continental Western Insurance Company | Union Insurance Company | Acadia Insurance Company | Firemen’s Insurance Company of Washington, D.C. | Tri-State Insurance Company of Minnesota